Amazon’s cloud and AI business is now growing almost seven times faster than Home Depot’s entire revenue, a gap that lays bare how differently the two retail giants are weathering a stubborn housing market and cautious consumer spending.
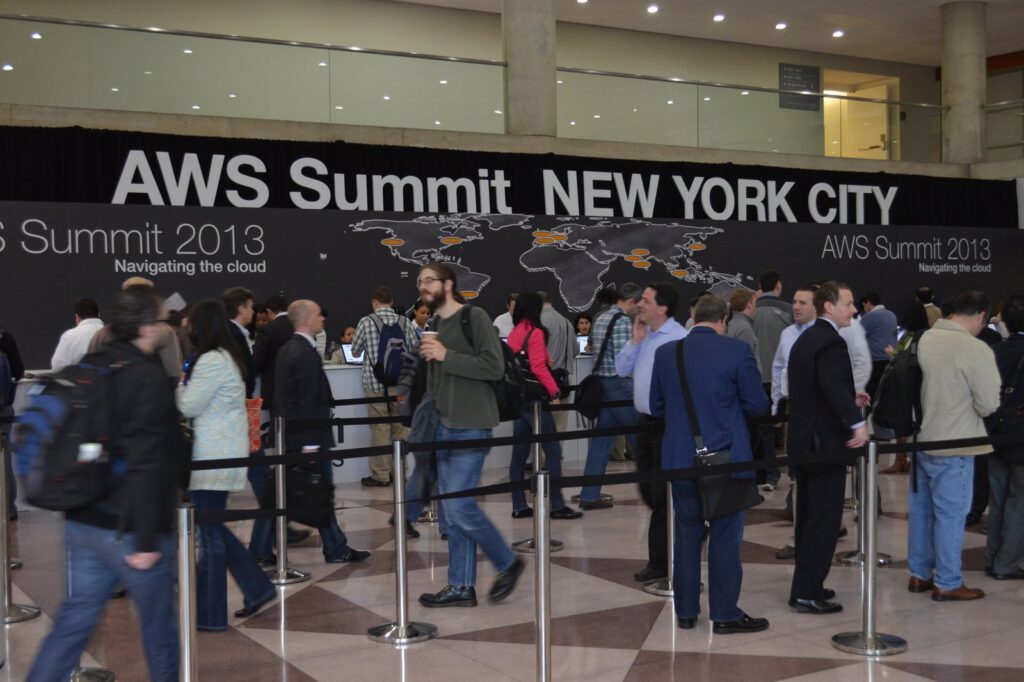
Amazon reported third-quarter 2026 revenue of $201.9 billion, up 12% from a year earlier, according to The Motley Fool. The engine behind that number was AWS, its cloud computing arm, where revenue jumped 39% to $46 billion as demand for artificial intelligence infrastructure accelerated. North American retail sales, Amazon’s largest segment, rose 6%.
Home Depot’s latest quarter tells a quieter story. Revenue rose 5.7% to $47.9 billion in the second quarter of fiscal 2026, with comparable sales up 1.7%. But customer transactions fell 0.8%, meaning growth came from shoppers spending more per visit, not from more shoppers walking through the doors.
Two Retailers, Two Weather Systems
The split comes down to what each company sells and who it sells to. Home Depot moves building materials, home improvement products and professional installation services to homeowners and contractors, and its sales rise and fall with seasonal demand, housing market activity and renovation spending. Amazon’s growth is spread across e-commerce, cloud computing and AI, businesses far less tethered to mortgage rates.
With interest rates still elevated and housing affordability strained, Home Depot management said customers are sticking to smaller repair and maintenance projects rather than committing to major renovations. High borrowing costs have discouraged home sales and refinancing, keeping homeowners in place and big projects on hold.
The contrast in scale is stark. Amazon’s quarterly revenue is more than four times Home Depot’s, and AWS alone brought in $46 billion, nearly matching the $47.9 billion Home Depot generated across its entire global operation. AWS also runs at substantially higher operating margins than Amazon’s retail business, so its growth carries outsized weight on the bottom line.
A Frozen Housing Market
Home Depot’s predicament is less about losing customers than about a market that has been virtually frozen since the pandemic ended. The lock-in effect from low mortgage rates, high home prices and now high borrowing costs has kept potential buyers on the sidelines. The Motley Fool notes an estimated shortage of roughly 4 million homes in the country.
The chain is not standing still. Home Depot has more than 2,000 stores worldwide and, alongside rival Lowe’s, forms a duopoly in home improvement retail. It has leaned into the professional contractor segment as its primary growth opportunity, acquiring building materials distributor SRS Distribution, and has invested in omnichannel tools that let customers order through its app for delivery or in-store pickup, along with digital project-planning apps.
Its most recent earnings report forecast an operating margin of 12.5%, below the roughly 15% the company has historically posted, and it recorded a return on invested capital of 25.7% in 2025. Home Depot’s stock is down 11% over the past five years, trailing the S&P 500.
What It Means for Small Operators
For independent contractors, remodelers and small retail businesses, the quarter offers a practical lesson: the tools driving Amazon’s expansion are available well beyond its own walls. Small businesses can use AI tools for inventory management and customer engagement, according to The Motley Fool, the same capabilities reshaping how larger retailers forecast demand and reach shoppers.
For a neighborhood hardware store or a two-person remodeling crew, that can mean tighter control over stock ahead of seasonal demand and steadier contact with past customers, without the overhead of a dedicated technology staff.
Home Depot’s own playbook shows the same shift from the other direction. Digital project-planning apps and app-based ordering are designed to capture a customer’s project before they ever reach the aisle, a recognition that the transaction increasingly starts on a screen.
The Road Back Runs Through Housing
A recovery in housing activity could give Home Depot a meaningful boost, though the timing remains uncertain. The company’s high-volume, high-margin model means a thaw in the market would flow quickly to sales and profitability.
Amazon, for its part, is not waiting on housing. Its e-commerce operations continue to expand while AWS rides accelerating demand for cloud and AI infrastructure, a combination that gives it multiple growth engines rather than one.
Home Depot reports its next quarterly results on a schedule that will put those transaction figures back under the microscope. For now, the numbers sit where they landed: $201.9 billion against $47.9 billion, and a 39% cloud surge against a 0.8% decline in customer traffic.
Sources
- Amazon vs. Home Depot: One Is Riding the AI Boom, While the Other Faces a Different Reality
- Amazon vs. Home Depot: One Is Riding the AI Boom, While the Other Faces a Different Reality | The Motley Fool
- Home Depot Is Down 24% From Its High. Here's Why I'd Hold It for a Decade. | The Motley Fool
Photo: Raysonho @ Open Grid Scheduler / Grid Engine (CC0)